
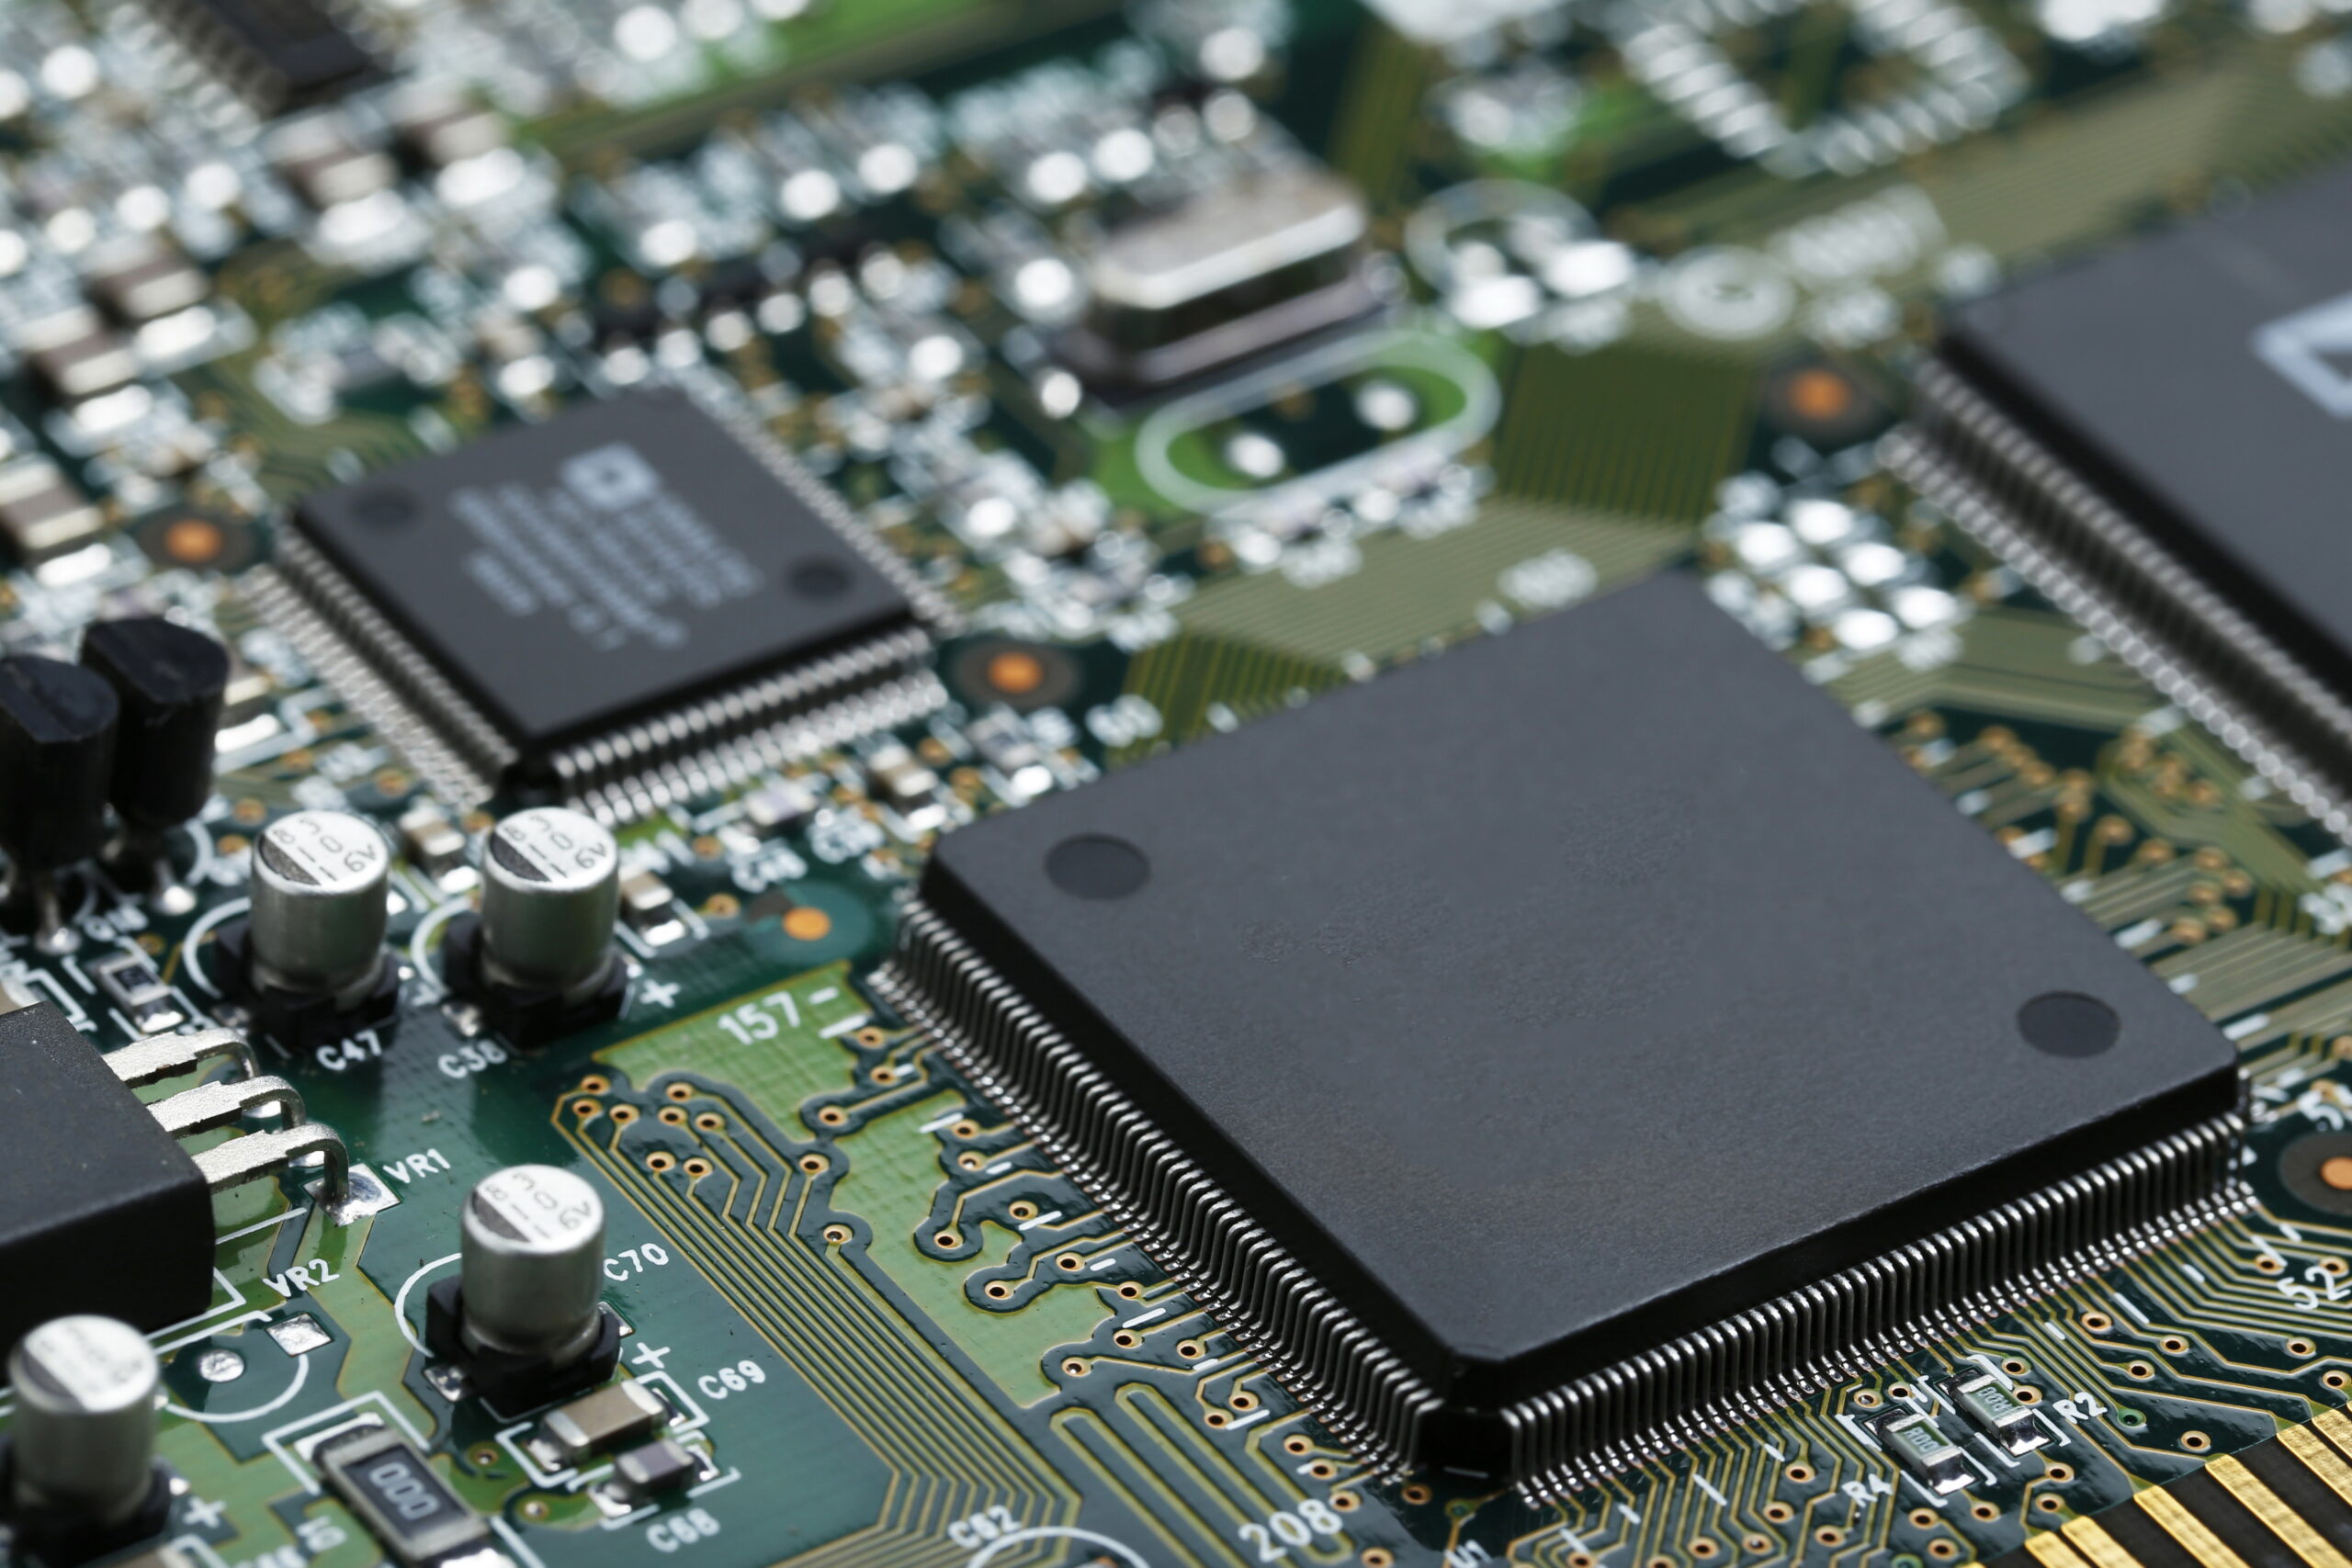
Neon makes up 0.0018% of the Earth’s atmosphere. It is captured as a byproduct of steel production — most efficiently by the air-separation units attached to older steel mills, of the kind that happened to be concentrated in Ukraine. Before 2022, Ukraine supplied roughly 70% of the world’s neon and about 90% of the semiconductor-grade neon used by US industry. That gas is indispensable to the lasers that etch patterns onto chip wafers.
Read that again as a structure: the most advanced manufacturing process in human history — the one underneath every phone, car, data center, and weapons system — was gated by a trace gas, purified as a side effect of Soviet-era steelmaking, in a country that was about to be invaded.
When the invasion came, chipmakers scrambled to build inventory, which compounded the shortage. And here the trap closed: ramping up neon purification elsewhere takes somewhere between nine months and two years — long enough that if a supply crunch looks temporary, nobody invests in alternatives, and the dependency survives the crisis that exposed it.
The semiconductor supply chain is full of structures like this. It is worth walking through them — not because most businesses make chips, but because almost every business depends on them, and because this chain displays, in extreme form, the patterns that quieter supply chains hide.
.
A chain of monopolies
Start at the top and walk down.
The most advanced chips are fabricated overwhelmingly in one place: Taiwan. TSMC alone holds more than half of the global foundry market, and an even larger share of leading-edge production — the result of thirty years of compounding as the undisputed hub of contract chipmaking. If TSMC’s operations were disrupted — by conflict, blockade, earthquake, energy shortage, or accident — industries from automotive to defense would feel it within days. This is not hypothetical hand-wringing: in recent years alone the company has navigated a major cyberattack, earthquakes, fire, pandemic disruption, and an energy-strained grid, while sitting at the center of the world’s most dangerous geopolitical flashpoint.
TSMC’s fabs, in turn, depend on lithography machines that only one company on earth can make. ASML’s extreme-ultraviolet (EUV) tools are the sole means of producing the most advanced chips — and ASML is not really a single company so much as the tip of a network: nearly 800 suppliers, with critical partners like Zeiss (optics) and TRUMPF (lasers) so deeply integrated that the ecosystem, built over four decades and protected by tens of thousands of patents, is effectively unreplicable. A monopoly assembled from near-monopolies.
Below the machines sit the materials, each with its own concentration story. Photoresists — the light-sensitive chemicals at the heart of the process — come overwhelmingly from a handful of Japanese suppliers. High-purity silicon wafers: a few producers. Specialty optics, photomask blanks, high-purity quartz: short supplier lists everywhere you look. The neon story above. And beneath nearly all of it, rare earth elements — where China controls the majority of global supply and more than 85% of global processing capacity, a distinction that matters because reserves elsewhere mean little without the refining infrastructure to use them.
The naive picture of a supply chain is a pyramid: many suppliers feeding fewer assemblers feeding final products. The semiconductor chain is closer to an hourglass stack — wide markets above and below, with the flow repeatedly squeezed through single companies, single countries, single facilities. The chain’s overall fragility is not the average of its links. It is the sum of its chokepoints.
.
Chokepoints are levers
Here is what elevates this from an engineering observation to a strategic one: a chokepoint visible to you is also visible to states — and states use them.
The precedent is now fifteen years old. In 2010, amid a territorial dispute, China temporarily halted rare earth exports to Japan — its largest customer, which consumed roughly two-thirds of Chinese rare earth exports to feed high-tech production across Asian supply chains. Prices of key elements exploded; one major rare earth went from under $5 per kilogram to $36. The episode established the template: dominance over a material chokepoint converts directly into geopolitical leverage, deployable on demand.
Since then, the practice has only institutionalized — export controls on chipmaking tools and materials, entity lists that cut named companies off from suppliers overnight, licensing regimes on critical minerals. The lesson for any business downstream is uncomfortable but clarifying: some of your supply risk is not risk in the actuarial sense at all. It is someone else’s policy option. Droughts are probabilistic; export bans are decisions. They follow announcements, legislative cycles, and escalation ladders — which means they can be monitored, anticipated, and prepared for by anyone doing the structured watching. This is where supply chain analysis stops being a procurement discipline and becomes an intelligence discipline.
.
You are in this chain whether you know it or not
The 2020–21 chip shortage made the dependency map briefly visible to everyone. Automakers idled assembly plants for want of chips costing a few dollars. Consumer electronics, industrial automation, medical devices, telecom equipment — production slowed or stopped across industries that had never thought of themselves as semiconductor businesses. They weren’t wrong about what they made. They were wrong about what they depended on.
That is the transferable lesson, and it applies far beyond electronics. Every business has, somewhere in the tiers behind its direct suppliers, its own neon: an input it has never examined, produced in few places, possibly as a byproduct of an unrelated industry, possibly in a jurisdiction whose politics it never tracks. The semiconductor chain is unusual only in that its chokepoints are now famous. Yours are probably still anonymous.
What the famous chain teaches about finding the anonymous ones:
Map to the chokepoint level, not the supplier level. Your tier-1 supplier list tells you almost nothing. The question is where flows narrow — which materials, components, and processing steps in your chain pass through one country, one company, or one facility, however many tiers down.
Track the geopolitics of tiers you don’t buy from. Nobody at an automaker was buying neon. Everybody at an automaker was exposed to it. Monitoring scoped to your dependency map — including the policy environment around chokepoints you touch only indirectly — is what converts front-page geopolitics into firm-specific foresight.
Treat policy risk as analyzable, because it is. Export controls and embargoes telegraph themselves through legislative drafts, official rhetoric, and escalation patterns. A business with exposure to a politically contested chokepoint can know it is contested, and roughly how contests have played out before, long before the lever is pulled.
Respect the ramp-up trap. The neon lesson generalizes: when alternatives take a year or two to qualify and the crunch might be temporary, markets systematically under-invest in resilience — which means the dependency will still be there for the next crisis. If your business needs the alternative to exist, the qualification work has to start before the crisis makes the case for it.
The semiconductor industry, to its credit, is now spending historic sums to diversify what it spent decades concentrating. Most other industries have not had their 2021 yet — the moment the invisible map becomes visible all at once. The choice available in the meantime is the same one we keep returning to in this series: examine the structure now, calmly, on your own schedule — or have it examined for you, by events, on theirs.
This piece is part of our series on supply chain intelligence — alongside our broader argument for treating supply risk as an intelligence problem, and our anatomy of how agri-food chains fail. Cercetium’s Research & Intelligence work covers exactly this territory: dependency mapping to the chokepoint level, geopolitical monitoring scoped to your exposure, scenario development, and alternative-source identification. If you’ve never seen your own chain’s hourglass points, we’d be glad to talk.


